Motor insurance can protect a vehicle against accidents, theft and several forms of external damage, but one of the costliest parts of a vehicle can still create an unpleasant surprise at claim time: the engine. The reason is that standard own-damage cover and engine-related consequential damage are not always the same thing.
If an accident directly damages an engine component, the loss may fall within the normal own-damage section, subject to policy terms. But when an insured incident leads to water entering the engine, lubricating oil leaking out, or a similar chain of events that later damages internal engine or gearbox parts, the resulting loss may be treated as consequential damage. Engine Protection Cover is designed to address this important gap.
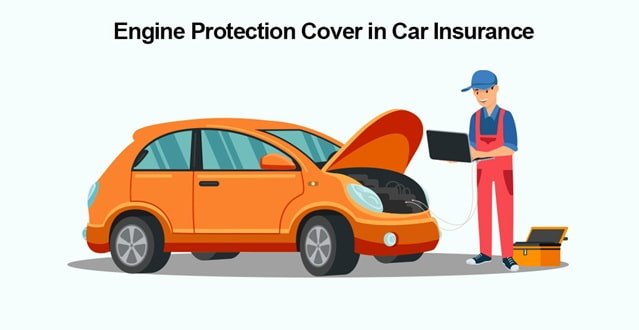
This add-on can therefore make a comprehensive or standalone own-damage motor policy more useful, particularly in flood-prone areas or for vehicles where major engine repairs can be expensive. Its value, however, depends on the exact wording of the add-on, because insurers do not all define the cover in exactly the same way.
What Is Engine Protection Cover?
Engine Protection Cover is an optional motor insurance add-on purchased for an additional premium along with a comprehensive policy or a standalone own-damage policy. It extends protection to specified engine-related consequential losses that may otherwise fall outside the basic own-damage cover.
Depending on the insurer and product, the add-on may cover internal engine parts and may also extend to the gearbox, transmission or differential when the damage results from defined events such as water ingress or accidental leakage of lubricating oil. Some products also pay for lost lubricant or coolant, while others exclude these items. The policy schedule and add-on wording therefore matter more than the name of the cover alone.
Why a Standard Motor Policy May Not Be Enough for Engine Damage
A standard motor own-damage policy is primarily designed to cover direct loss or damage caused by insured events. Engine problems can be more complicated because the immediate event and the final mechanical damage may occur in stages.
For example, a car may enter a waterlogged road and stall. Water entering the engine can damage internal components when the engine is cranked or when the water causes internal stress. Similarly, an impact under the vehicle may damage the oil sump, leading to loss of lubricant and later internal engine damage. The original event may be accidental, but the severe internal damage that follows can be classified as consequential loss unless an applicable add-on extends the cover.
Engine Protection Cover is valuable because it is written specifically to respond to certain such chains of damage, subject to the conditions and exclusions stated by the insurer.
What Engine Protection Cover Can Typically Add to Your Policy
| Situation | How the add-on may help |
| Water ingress into the engine | May cover specified consequential damage to internal engine parts when water entry meets the policy conditions. |
| Accidental lubricant leakage | May cover engine damage caused after oil or lubricant leaks because of an accidental event. |
| Gearbox or related assembly damage | Some add-ons extend protection to gearbox, transmission or differential parts when the stated cause is covered. |
| Undercarriage impact followed by oil leakage | Certain wordings cover resulting engine or gearbox damage when there is evidence that accidental underbody damage caused the leakage. |
| Lubricants, oil or coolant used in repair | Coverage differs. Some products include these costs while others specifically exclude them. |
How Engine Protection Cover Enhances Financial Protection
The biggest improvement is not that it turns motor insurance into a maintenance contract. It does not. Its value is that it can prevent a covered accident or water-related event from becoming a large uninsured engine-repair bill.
Modern engines and gearboxes contain high-value precision components. A serious internal failure may require dismantling, replacement of several parts or, in extreme cases, replacement of a major assembly. When the cause falls within the add-on wording, engine protection can move a substantial part of that cost from the vehicle owner to the insurer, subject to deductibles, limits and other policy conditions.
It also improves the practical usefulness of motor insurance during monsoon flooding. A policyholder may have comprehensive cover and still discover that the most expensive part of a flood-related claim is a consequential engine loss. Adding the correct engine protection wording can reduce that exposure.
What Is Usually Not Covered?
Engine Protection Cover is not a blanket warranty for every engine problem. Common exclusions or restrictions can include normal wear and tear, ageing, corrosion, routine mechanical or electrical breakdown, pre-existing defects and damage arising from poor maintenance. A failure that develops simply because a part has reached the end of its useful life is generally different from a covered accidental or water-ingress event.
Claims can also become difficult if the vehicle owner delays informing the insurer, continues to drive after an oil leak, repeatedly attempts to restart a vehicle that has stalled in deep water, or begins repairs before the insurer has had an opportunity to inspect the damage. The exact effect depends on the policy wording and facts of the claim, but owners are expected to take reasonable steps to prevent further loss.
Damage payable under a manufacturer’s warranty, recall campaign or another insurance arrangement may also be excluded. Some add-ons impose vehicle-age limits, claim-count limits or other eligibility conditions.
Who Should Seriously Consider This Add-On?
Engine protection deserves particular attention if you live or regularly drive in an area that experiences heavy monsoon rain, flooding or waterlogging. It can also be useful for owners of vehicles with low ground clearance, expensive engines or gearboxes, or cars that would create a significant financial burden if a major engine repair were required.
Owners of newer vehicles may find the add-on attractive because the engine and associated assemblies still represent a high-value part of the vehicle. Owners of older vehicles should first check whether their insurer still offers the add-on at that vehicle age and whether the premium remains worthwhile relative to the vehicle’s value.
A Simple Claim Example
Suppose a car is driven into an unexpectedly waterlogged stretch of road and the engine stalls. The owner does not try to restart it, informs the insurer and arranges towing. Inspection later confirms water ingress and damage to internal engine components.
The basic own-damage policy may not automatically pay every consequential internal engine loss arising from that water ingress. If the policy includes a suitable Engine Protection Cover and the event meets its conditions, the add-on may respond to the eligible repair or replacement costs.
Now consider another case in which the vehicle strikes road debris and the undercarriage is damaged. Engine oil leaks out and internal parts are damaged as a result. Some engine-protection wordings can cover this chain of loss when the accidental damage and leakage are supported by evidence.
What to Check Before Buying Engine Protection Cover
Do not select the add-on only because the premium looks small. Read the coverage trigger carefully. Check whether the wording covers water ingress, hydrostatic-lock-related loss, lubricating oil leakage and damage to the gearbox, transmission or differential. Also check whether lubricants, coolant and consumables are included or excluded.
Look for vehicle-age restrictions, the maximum number of claims, deductibles, depreciation rules, claim limits and any requirement for inspection or prior approval. If your main reason for buying the add-on is flood protection, pay special attention to what the insurer expects you to do when the vehicle stalls in water.
It is also worth separating Engine Protection Cover from other add-ons. Zero-depreciation cover, consumables cover, roadside assistance and no-claim-bonus protection solve different problems. Combining them can improve a policy, but one add-on should not be assumed to provide the benefits of another.
How to Handle a Possible Engine Protection Claim
If the vehicle stalls in deep water or suffers an impact that causes visible fluid leakage, stop using the vehicle and contact the insurer as soon as possible. Avoid trying to diagnose the problem by repeatedly starting the engine. Take photographs if it is safe to do so and arrange towing when required.
Do not authorize major engine dismantling or repairs before following the insurer’s claim process. Evidence of water exposure, accidental underbody damage, oil leakage and the sequence of events can be important in establishing that the damage falls within the add-on.
Is Engine Protection Cover Worth Adding?
For every vehicle owner, the answer is not automatically yes. Someone driving an older, low-value vehicle in an area with little flood exposure may place a lower value on the add-on. But for a newer car, a high-value vehicle or a vehicle regularly exposed to waterlogged roads, the potential repair cost can be far larger than the additional premium.
The real benefit is precision. Comprehensive insurance provides broad own-damage protection, while Engine Protection Cover addresses a specific and potentially expensive gap. The right decision comes from comparing the add-on wording with the risks your vehicle actually faces rather than buying every available rider without checking its purpose.
Frequently Asked Questions
Q1. Will Engine Protection Cover pay the full cost if the entire engine has to be replaced?
Not automatically. The insurer first decides whether the cause of loss is covered and whether replacement is necessary. The final payment can also depend on deductibles, depreciation provisions, policy limits, excluded consumables and the vehicle’s insured value. A major engine replacement should therefore not be treated as an unconditional full-cost benefit.
Q2. Can Engine Protection Cover be added after the motor policy has already started?
Possibly, but this is insurer-specific. Some insurers may permit an endorsement during the policy period, while others may allow the add-on only at policy purchase or renewal. A vehicle inspection may also be required. Do not assume that the cover can be added after an engine problem or flood incident has already occurred.
Q3. Can an Engine Protection claim affect my No Claim Bonus?
It can. No Claim Bonus is generally linked to remaining claim-free under the own-damage section. If an engine-protection loss is registered as an admissible own-damage claim, the NCB available at the next renewal may be affected unless a separate NCB-protection benefit applies. The exact treatment should be confirmed with the insurer before filing or settling the claim.
Q4. Can an Engine Protection claim be settled cashlessly at a network garage?
Often it can if the insurer offers cashless motor repairs at that garage and approves the engine-protection portion of the claim. Cashless does not mean every expense is automatically payable. Deductibles, excluded items and amounts outside the add-on wording can still remain payable by the policyholder.
Q5. If the regular own-damage claim is approved, is the Engine Protection claim automatically approved too?
No. The base own-damage loss and the engine-protection extension can be assessed separately. An insurer may accept the accidental external damage but still examine whether the internal engine or gearbox damage was actually caused by a trigger covered under the add-on. Evidence establishing the chain of damage is therefore important.
Q6. Does roadside assistance or towing cover automatically make flood-related engine damage payable?
No. Roadside assistance can help with towing or emergency services, but it does not decide whether the engine damage itself is insured. The engine claim still has to satisfy the Engine Protection Cover wording. Towing the vehicle promptly can, however, help prevent further damage and preserve evidence for assessment.