Real estate has traditionally been viewed as a long-term wealth-building asset in India. However, investors no longer need to purchase an entire apartment, office or commercial building to gain exposure to the property market. Real Estate Investment Trusts, or REITs, provide a regulated way to invest in income-generating real estate through units that can be traded on the stock exchange.
This raises an important question: Real estate vs REITs—which is more profitable?
There is no universal winner. Direct real estate can offer rental income, control and potential appreciation, while REITs provide access to professionally managed property portfolios with greater liquidity and lower entry requirements. The more suitable option depends on the investor’s capital, investment horizon, liquidity requirements and willingness to manage property.
What Is Direct Real Estate Investment?
Direct real estate investment means purchasing a physical property such as a residential apartment, commercial shop, office, warehouse or land.
The investor can potentially earn returns through:
- Rental income
- Property appreciation
- Redevelopment or improvement
- Strategic sale of the property
For example, an investor purchasing a commercial property for ₹1 crore and receiving ₹75,000 monthly rent would generate ₹9 lakh in annual gross rent.
The gross rental yield would be:
₹9 lakh ÷ ₹1 crore × 100 = 9%
However, the actual return can be lower after considering vacancy, maintenance, property taxes, brokerage, repairs, financing costs and other expenses.
What Are REITs?
A REIT is a trust registered with the Securities and Exchange Board of India (SEBI) that raises money by issuing units and invests primarily in real estate assets. Investors own REIT units rather than directly owning individual buildings.
India’s REIT framework allows investors to obtain exposure to income-generating real estate without purchasing an entire property themselves.
SEBI’s current regulations require REITs to follow specific investment and distribution requirements. The regulations were last amended on April 18, 2026.
1. Rental Income vs REIT Distributions
Direct property owners receive rent directly from tenants according to their lease agreements.
REIT investors receive distributions generated from the underlying properties and the REIT’s cash flows. SEBI’s framework includes minimum distribution requirements relating to net distributable cash flows.
This can make REITs useful for investors looking for exposure to income-producing real estate without becoming landlords themselves.
However, REIT distributions should not be treated as guaranteed income. The amount can vary depending on occupancy, rental collections, property expenses, financing and other factors.
2. Capital Appreciation
Direct property investors can potentially benefit when the market value of their property rises.
For example, if a property purchased for ₹80 lakh later becomes worth ₹1.1 crore, the investor has a potential capital gain of ₹30 lakh before transaction costs and applicable taxes.
REIT investors can also benefit from appreciation, but through changes in the market price of REIT units. The unit price can rise or fall based on property performance, interest rates, market sentiment, occupancy expectations and broader economic conditions.
Therefore, REITs are not simply a fixed-income alternative. Their market prices can fluctuate.
3. REITs Require Much Less Capital
Buying physical real estate generally requires substantial capital.
The buyer may need to arrange a down payment and pay additional costs such as:
- Stamp duty
- Registration charges
- Brokerage
- Legal expenses
- Interior or renovation costs
- Property-related charges
REITs allow investors to purchase units through the securities market rather than acquiring an entire property.
SEBI’s REIT framework has also evolved over time to make listed REIT investment more accessible.
This difference in capital requirements can be significant for individuals who want real-estate exposure but do not have enough capital to purchase a property.
4. Liquidity Is a Major Difference
Direct property is relatively illiquid.
Selling an apartment, office or shop can require finding a buyer, negotiating the price, completing due diligence and handling documentation. The process can take considerable time.
Listed REIT units, on the other hand, can generally be bought or sold through the stock exchange during market hours, subject to market liquidity.
This makes REITs substantially more flexible for investors who may need to change their investment position.
However, liquidity does not eliminate market risk. A REIT unit may have to be sold at a price below the investor’s purchase price.
5. REITs Provide Diversification
A direct property investment is often concentrated in one building and one location.
If the property’s neighbourhood experiences weak demand, increased competition or infrastructure problems, the investment may be significantly affected.
A REIT can hold multiple properties and, depending on the trust, exposure may span different locations and tenants.
SEBI’s framework requires REITs to follow specified investment structures and asset requirements, providing a regulated framework for pooled real-estate investment.
This diversification can reduce the dependence on the performance of a single property.
6. Property Management Is Different
Direct property ownership requires active involvement.
The owner may have to deal with:
- Finding tenants
- Negotiating leases
- Collecting rent
- Repairs
- Maintenance
- Property management
- Tenant disputes
- Vacancy periods
With a REIT, professional managers handle the underlying portfolio within the regulatory framework.
Therefore, REIT investors generally have less day-to-day operational responsibility.
7. Leverage Can Change the Return
Direct real estate is often purchased using a home loan or other financing.
Leverage can increase the return on the investor’s own capital if the property appreciates sufficiently relative to financing costs.
But leverage also increases risk. Loan interest continues even when the property is vacant or its value declines.
REIT investors do not normally take a property loan in their own name simply to purchase a REIT unit. However, REITs themselves can have debt within their structure, meaning investors remain exposed to the financial effects of borrowing at the trust or underlying-entity level.
8. Costs Can Affect Profitability
The advertised return on a property or REIT should not be considered the final profit.
For direct property, investors should consider acquisition costs, maintenance, vacancy, repairs, taxes, brokerage, insurance and financing.
For REITs, investors should consider the purchase price of units, brokerage and other applicable transaction charges, taxation and the trust’s operating and financing structure.
A property offering a high rental yield may still produce modest net returns if expenses are substantial.
Similarly, a REIT distributing a particular amount does not mean that the distribution itself represents the investor’s total return.
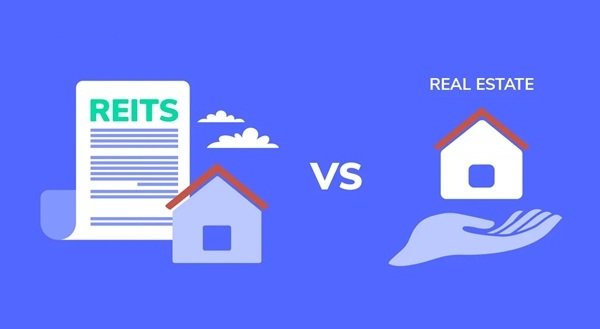
Real Estate vs REITs: Key Differences
| Factor | Direct Real Estate | REITs |
| Ownership | Physical property | Units in a real-estate trust |
| Initial capital | Usually high | Generally lower |
| Rental exposure | Direct | Through underlying properties |
| Liquidity | Relatively low | Generally higher for listed units |
| Diversification | Limited unless multiple properties are owned | Usually greater |
| Management | Owner involvement may be required | Professional management |
| Leverage | Common at investor level | Debt may exist within REIT structure |
| Price movement | Less frequent visible pricing | Market price changes regularly |
| Control | Higher | Limited |
| Transaction process | Complex and time-consuming | Exchange-based for listed units |
Which Is More Profitable?
Profitability depends on what the investor means by “profit.”
A direct property can generate strong rental income and significant appreciation, particularly when the property is purchased at an attractive valuation and located in a high-demand area. However, the investor also takes on concentration, maintenance, vacancy and liquidity risks.
REITs can provide diversified exposure to income-producing real estate with substantially lower capital requirements and greater liquidity. Their returns can come from distributions as well as changes in the market price of units.
Therefore, investors should compare total return rather than rental income alone.
For example:
Direct property total return = rental income + appreciation − expenses − transaction costs − financing costs
REIT total return = distributions + change in unit price − applicable costs and taxes
Neither calculation guarantees a particular future return.
Conclusion
The choice between direct real estate and REITs depends largely on the investor’s objectives.
Direct property may appeal to investors who want physical ownership, greater control and the possibility of using leverage. REITs may appeal to investors who want diversified real-estate exposure, lower capital requirements and easier liquidity.
India’s REIT market operates under SEBI’s regulatory framework, which provides rules governing investment, management and distributions.
Rather than asking which option is automatically more profitable, investors should compare net rental or distribution income, potential appreciation, taxes, costs, liquidity, diversification, leverage and investment horizon. Evaluating these factors together provides a more realistic picture of the potential profitability of real estate versus REITs.