A home starts aging quietly. One day the bathroom tiles look dull, the kitchen feels too small, the wiring needs repair, or the roof starts demanding attention. Renovation is not always a luxury. Sometimes it is about comfort, safety, space, and keeping the property strong for the next 10–15 years. But renovation also needs money, and that is where a home loan top up can become useful.
A home loan top up is an extra loan taken over your existing home loan. You do not need to take a separate personal loan at a very high interest rate if your lender finds you eligible. The money can usually be used for renovation, repair, interiors, extension, furniture, home improvement, or other approved personal needs, depending on the bank’s policy.
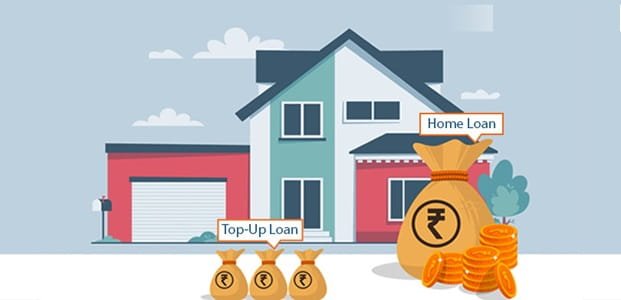
What Is a Home Loan Top Up?
A home loan top up is an additional loan offered to an existing home loan borrower. Since the bank already has your property records, repayment history, and loan details, the process is often smoother than taking a new unsecured loan.
Many banks allow top up loans to existing home loan customers, and some also offer it when you transfer your home loan from another lender. For example, HDFC Bank mentions that existing home loan, home improvement loan, or home extension loan customers can apply for a top up, and even balance transfer customers may be eligible.
Can You Use a Home Loan Top Up for Renovation?
Yes, a home loan top up can usually be used for home renovation or improvement. You can use it for work such as:
- Kitchen renovation
- Bathroom repair
- Flooring and tiles
- Painting and waterproofing
- Electrical rewiring
- Plumbing work
- Modular kitchen
- Wardrobes and interiors
- Balcony repair
- Room extension, if allowed
- Basic furniture and fixtures
However, the lender may ask for the purpose of the loan. Some banks may require a renovation estimate, especially if the loan is being treated as a home improvement or repair loan.
Home Loan Top Up vs Home Renovation Loan
Both options can help you renovate your house, but they are slightly different.
A home loan top up is an extra amount over your existing home loan. It is usually given based on your repayment track record, property value, outstanding loan, and income eligibility.
A home renovation loan or home improvement loan is specifically meant for repair, renovation, or improvement of the house. In this case, the lender may focus more on the renovation estimate and property-related work.
If you already have a running home loan and a good repayment record, a top up may be easier. If your renovation is large and properly planned, a home improvement loan may also be considered.
Basic Eligibility for Home Loan Top Up
Eligibility differs from bank to bank, but lenders usually check these points:
- Your existing home loan repayment should be regular.
- You should have a clean EMI track record.
- Your income should support the new EMI.
- Your credit score should be acceptable.
- The property value should support the total loan amount.
- The original home loan should have completed the lender’s minimum waiting period.
- There should be no legal issue in the property.
Different banks have different rules. HDFC Bank mentions that customers can apply after 12 months from final disbursement and after possession or completion of the financed property. Axis Bank states that existing home loan customers may be eligible after six months of clear repayment, while takeover cases may require one year of clear repayment track record.
How Much Top Up Loan Can You Get?
The amount depends on your income, outstanding home loan, property value, age, credit profile, and repayment capacity. The bank will check whether you can afford the existing EMI plus the new top up EMI.
For example, if your monthly income is good and your existing loan outstanding has reduced over time, your chances of getting a higher top up improve. But if your salary is already heavily used for EMIs, credit card bills, or personal loans, the bank may approve a smaller amount or reject the request.
The lender may also look at the current market value of the property. If the property value has increased and your repayment record is clean, it can help your case.
Step-by-Step Process to Get a Home Loan Top Up for Renovation
Step 1: Check Your Existing Loan Status
Before applying, check your home loan account. Your EMI record should be clean. If there are recent bounces, late payments, or overdue charges, first clear them. Banks are more comfortable giving top up loans to borrowers who have shown discipline.
Step 2: Estimate Your Renovation Cost
Do not apply randomly. Make a proper budget. Take estimates from contractors, interior designers, plumbers, electricians, or civil workers. Divide the cost into major heads like labour, material, furniture, tiles, paint, fittings, and emergency buffer.
A proper estimate helps you borrow only what you need.
Step 3: Check Your Loan Eligibility
Use the lender’s online eligibility calculator or speak to the branch. The bank will consider your income, age, current EMI, new loan amount, tenure, and credit score.
If your EMI burden is already high, try to reduce other loans before applying.
Step 4: Compare Top Up With Other Options
Before finalising, compare the top up with a personal loan, gold loan, or home improvement loan. A top up home loan often has a lower interest rate than a personal loan, but it may run for a longer tenure. Longer tenure reduces EMI but increases total interest.
So, do not look only at EMI. Look at total repayment also.
Step 5: Apply With Your Current Lender
The simplest route is to apply with your existing home loan lender. Since your property papers and loan file are already with them, processing may be faster.
You can apply online, through mobile banking, net banking, loan service portal, branch, or relationship manager, depending on the bank.
Step 6: Submit Documents
The lender may ask for updated KYC, salary slips, bank statements, Form 16, ITR, property documents, existing loan statement, renovation estimate, and photographs or quotations in some cases. HDFC’s home loan documentation checklist mentions income documents such as recent salary slips, bank statements showing salary credits, Form 16, and ITR for salaried applicants.
Self-employed borrowers may need business proof, GST returns, ITRs, profit and loss account, balance sheet, and bank statements.
Step 7: Property and Credit Verification
The lender may re-check the property value, legal status, repayment history, and credit score. If the bank is satisfied, it will sanction the top up amount.
Step 8: Sign the Agreement and Receive Disbursal
After approval, you will receive a sanction letter showing loan amount, interest rate, tenure, EMI, processing fee, and other terms. Read it carefully before signing. Once documents are completed, the amount is usually credited to your bank account or disbursed as per lender rules.
Charges You Should Check
Before taking the loan, check these charges carefully:
- Processing fee
- Legal or technical verification charges
- Stamp duty on loan agreement
- Insurance charges, if any
- Prepayment or foreclosure rules
- Part-payment conditions
- Interest rate type: fixed or floating
- EMI start date
- Total interest over the tenure
A lower EMI should not blind you. Sometimes borrowers stretch a small renovation loan for too many years and end up paying unnecessary interest.
Smart Tips Before Taking a Top Up
Borrow only for serious renovation, not for lifestyle spending. Keep a 10% extra buffer for material cost changes. Avoid using the full amount for luxury interiors if basic repairs are pending. Keep all invoices and receipts safely. If the renovation improves property value, it is a better use of the loan.
Also, keep your EMI comfortable. Your home should become better after renovation, not become a financial burden.
FAQs
Q1. Is a home loan top up better than a personal loan for renovation?
In many cases, yes. A home loan top up usually offers a lower interest rate and longer tenure than a personal loan. But the final choice depends on urgency, amount needed, processing time, and total interest cost.
Q2. Can I get a top up loan if my home loan is only 6 months old?
It depends on the lender. Some banks may consider top up after six months of clear repayment, while others may require 12 months or more. The repayment record must be clean.
Q3. Will the bank ask for renovation bills?
Sometimes yes. For a pure top up loan, documentation may be lighter. But if the purpose is home improvement or renovation, the lender may ask for estimates, quotations, or supporting documents.
Q4. Can I take a home loan top up from another bank?
Yes, usually through a home loan balance transfer. You transfer your existing home loan to a new lender and request an additional top up amount. The new lender will check your repayment history, income, property value, and credit profile before approving it.